What Secret Insurance Documents in Oklahoma Should Teach Every South Carolina Accident Victim
By Gary Christmas, Christmas Injury Lawyers
For years, I’ve told injured people something they sometimes don’t want to hear:
The insurance company handling your claim does not look at your accident the same way you do.
To you, an accident can change everything.
It can mean pain that keeps you awake at night. Medical appointments that suddenly take over your calendar. Time away from work. A car you can’t drive. A family trying to figure out how to keep life moving while you’re hurt.
To an insurance company, your claim is also something else.
It is a cost.
That doesn’t mean every insurance adjuster is a bad person. It doesn’t mean every claim is unfairly denied. And it certainly doesn’t mean every insurance company handles every claim the same way.
But it does mean that injured people need to understand who is sitting on the other side of the table.
A remarkable legal battle unfolding in Oklahoma is providing the public with a rare look behind the curtain at how decisions about insurance claims may be made.
And although the cases involve damaged roofs rather than injured people, I believe there is an important lesson here for anyone dealing with an insurance company after a serious accident.
What Is Happening in Oklahoma?
In August 2026, Oklahoma Watch and The Journal Record published an investigation examining documents that have emerged from ongoing litigation involving wind and hail insurance claims.
Some of the documents concern an Allstate program that goes all the way back to 1997.
Allstate conducted a test in Albuquerque, New Mexico, called the Claim Core Process Redesign, which changed how certain wind and hail claims were evaluated.
According to documents described in the investigation, the results were dramatic.
Before the test, Allstate reportedly made payments on 75.9% of wind claims and 82.8% of hail claims.
After the test, those figures reportedly fell to 29.2% of wind claims and 11.1% of hail claims.
The reporting states that initial test results showed claim payout costs falling by 50% or more.
Think about those numbers for a moment.
The significance isn’t simply that an insurance company found a way to spend less money.
Businesses look for ways to control costs every day.
The question being raised by the Oklahoma litigation is how those savings were achieved and whether legitimate claims were denied or underpaid in the process.
That question is now being fought out in court.
Oklahoma’s Attorney General Has Sued Allstate
On July 7, 2026, Oklahoma Attorney General Gentner Drummond filed a lawsuit against Allstate.
The lawsuit alleges that Allstate engaged in a coordinated effort to wrongfully deny or underpay legitimate wind and hail claims from Oklahoma homeowners.
According to the Attorney General’s office, the lawsuit alleges that Allstate limited the authority of field adjusters, relied on third-party inspectors and reviewers, and applied restrictive internal standards that were not disclosed to policyholders.
The State of Oklahoma is seeking civil penalties, restitution and other relief.
Those are serious allegations.
They are also allegations, and that distinction matters.
Allstate has denied them.
In a statement reported by The Journal Record, Allstate called the lawsuit baseless and said the company is committed to providing timely and fair claim payments based on its policies.
Ultimately, a court will determine the merits of the legal claims.
But some of the information becoming public through this broader dispute deserves attention regardless of the eventual outcome.
One Detail Especially Caught My Attention
The reporting describes claims being evaluated by people who were not necessarily the adjusters standing at the damaged property.
At a 2025 U.S. Senate hearing on insurance claim practices, former Allstate adjuster Nick Schroeder described situations in which he submitted roof damage that he believed should be included in a claim, only for remote reviewers to disagree and direct that items be removed.
The Oklahoma reporting also describes allegations involving restrictions on the authority of front-line adjusters and increased remote review of claims.
Why does that interest me as a personal injury lawyer?
Because after decades of representing injured people, I want consumers to understand something very important:
The person you speak with at an insurance company may be only one part of a much larger claims system.
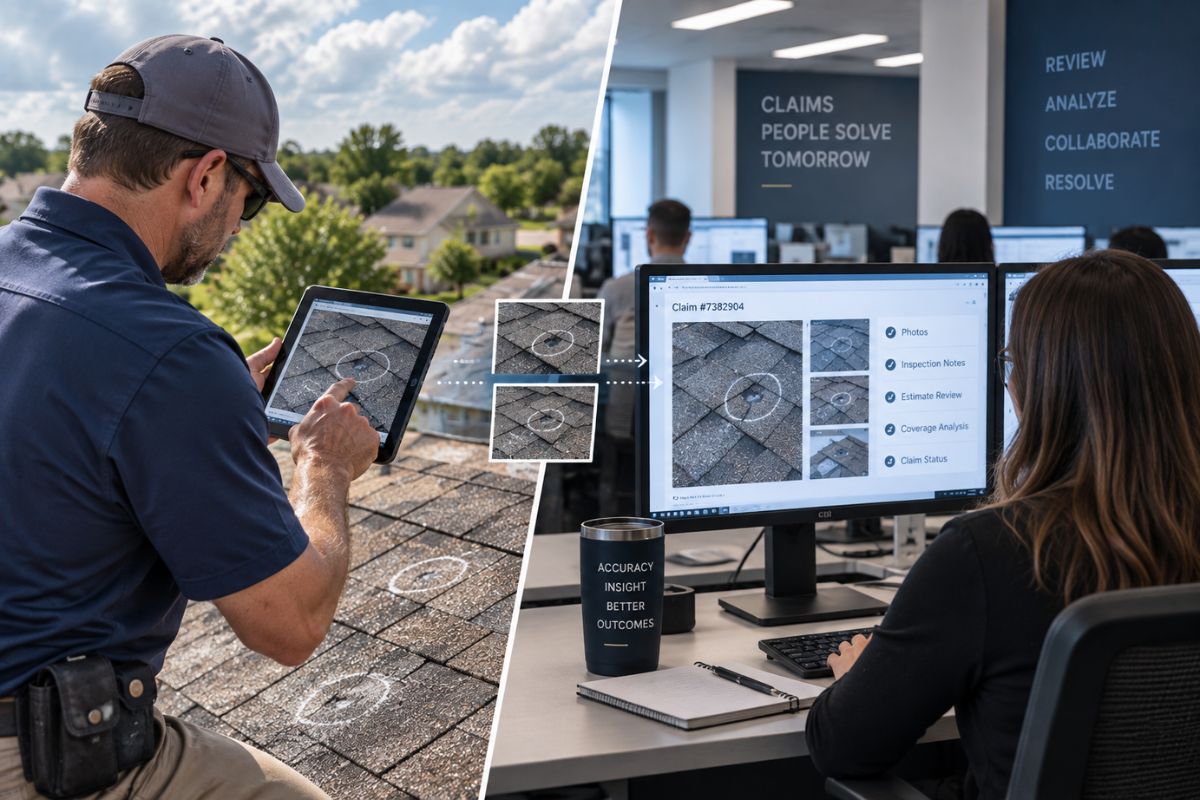
There may be supervisors.
There may be internal guidelines.
There may be software.
There may be medical reviewers.
There may be limits on settlement authority.
There may be procedures governing when additional approval is required.
And there may be people making important decisions about your claim whom you will never meet or speak with.
That is why I tell people not to mistake a friendly conversation with an adjuster for an understanding of how the entire claim is being evaluated.
A Roof Claim Is Not a Personal Injury Claim
We need to be very clear about this.
The Oklahoma litigation involves property insurance claims concerning wind and hail damage. A South Carolina car accident or personal injury claim is different.
The laws are different.
The policies may be different.
The evidence is different.
And nothing coming out of the Oklahoma litigation establishes that an automobile insurer in South Carolina is using the same practices alleged in those cases.
But there is a broader principle that every injured person should understand:
Insurance companies have an economic interest in what they ultimately pay on claims.
There is nothing surprising about that statement. Insurance companies are businesses.
The mistake is assuming that because an insurance company is involved in your accident claim, someone inside that company has independently taken responsibility for determining everything you’ve lost and making sure you are fully compensated for it.
That is not a safe assumption.
What I See When Insurance Companies Evaluate Injury Claims
When somebody comes into our office after an accident, I sometimes hear:
“The insurance company already accepted responsibility, so I think everything should be pretty straightforward.”
I understand why someone would think that.
Unfortunately, accepting that your insured caused a crash and agreeing about the value of the resulting injury claim are two very different things.
Even where fault for an accident is reasonably clear, disputes can arise over the medical treatment you received, the seriousness of your injuries, pre-existing conditions, lost income, future medical needs and what the insurance company believes your claim is worth.
If you’re dealing with an insurer after a South Carolina car accident, we’ve created an Insurance Claims Knowledge Center that answers many of the questions people have about the claims process, including how insurance companies evaluate claims, what information they may ask for and what you should understand before accepting a settlement.
This is one of the reasons documentation matters so much in a personal injury case.
An insurance company does not experience your injury.
It evaluates evidence about your injury.
Medical records, diagnostic tests, photographs, witness statements, employment records and other documentation can become the pieces from which an insurer constructs its view of what happened to you.
“But the Adjuster Has Been Really Nice to Me”
I’ve heard this many times over the years.
And the adjuster may genuinely be a nice person.
Most of the insurance professionals I’ve dealt with during my career are people doing their jobs.
But you have to separate the person from the role.
An insurance adjuster’s job is not the same as your lawyer’s job.
Your attorney represents you.
An adjuster works for the insurance company.
That distinction matters.
You can be polite. You can be truthful. You can treat everyone involved with respect.
But you should understand the relationship.
A pleasant conversation doesn’t change who the adjuster works for.
Read: What Should I Avoid Saying To Insurance Adjusters
The First Offer Isn’t a Verdict on What Your Case Is Worth
Another mistake I see injured people make is treating an insurance company’s settlement offer as though it were an independent appraisal of their case.
It isn’t a court ruling.
It isn’t a jury verdict.
And it isn’t necessarily the final amount an insurer may ultimately agree to pay.
It is an offer.
Whether that offer reasonably reflects the circumstances of a particular case depends on the evidence, the injuries, the available insurance coverage, disputed legal issues and many other factors.
This is particularly important when someone is contacted about settlement while still receiving medical treatment.
Once you settle most personal injury claims and sign a release, you generally cannot simply reopen the case months later because your injuries turned out to be more serious than you originally realized.
That’s why I would be very cautious about making a major decision about a serious injury claim before understanding both your medical condition and your legal options.
South Carolina Has Rules Governing Insurance Claim Practices
The Oklahoma cases will be decided under the laws applicable to those disputes.
South Carolina has its own insurance laws.
South Carolina Code § 38-59-20 identifies a number of acts that can constitute improper claim practices when committed without just cause and with sufficient frequency to indicate a general business practice.
Among other things, the statute addresses:
Failing to adopt and implement reasonable standards for the prompt investigation and settlement of claims.
It also addresses:
Failing to attempt in good faith to effect prompt, fair and equitable settlement of claims when liability has become reasonably clear.
And the statute addresses situations involving claimants being compelled to file lawsuits because an insurer offered substantially less than amounts ultimately obtained through litigation or settlements involving their attorneys.
South Carolina law also contains provisions addressing attorney’s fees in certain disputes where an insurer refuses to pay a covered claim and a court finds that refusal was without reasonable cause or in bad faith. The application of those provisions depends on the circumstances of the particular insurance relationship and claim.
Insurance law can become complicated quickly, particularly because claims made against another driver’s liability coverage are not necessarily the same as disputes involving your own insurance policy.
But the larger point is simple.
Insurance companies do not get to make up the rules as they go.
Five Things I Want Every Injured Person in South Carolina to Understand
After representing injured people for decades, there are five things I wish everyone understood before dealing with an insurance company after a serious accident.
1. What You Say Matters
Insurance adjusters investigate claims.
That means statements you make about how the accident happened, your injuries, your previous medical history and how you’re feeling may become part of the claim.
Be truthful.
But don’t feel pressured to speculate about things you don’t yet know.
Two days after a crash, for example, you may have no idea how an injury will affect you two months later.
2. Your Medical Treatment Creates a Record
If you are hurt, getting appropriate medical care matters first and foremost for your health.
It also creates documentation of what you’re experiencing.
Long unexplained gaps in treatment can create questions in an insurance claim. Insurers may argue that a gap indicates an injury improved, wasn’t serious or wasn’t related to the accident.
That doesn’t mean you should receive treatment you don’t need.
It means you should take your health seriously and follow appropriate medical advice.
3. Don’t Assume the Insurance Company Knows Everything You’ve Lost
An adjuster isn’t living your life.
The insurance company may not automatically know that you couldn’t pick up your child for six weeks.
It may not know you had to sleep downstairs because you couldn’t climb the stairs.
It may not know you missed an important family event.
It may not know that the activities you enjoyed before the accident became painful or impossible.
Those details can matter.
4. Don’t Assume the First Offer Is the Last Word
A settlement offer is exactly that: an offer.
Before accepting one, understand what rights you are giving up.
This becomes particularly important when significant injuries, ongoing treatment or future medical needs are involved.
Read: Should I Accept The Insurance Company’s First Offer?
5. You Are Allowed to Ask Questions
If something doesn’t make sense, ask.
If you don’t understand why a claim was denied, ask for an explanation.
If you don’t understand a document you’re being asked to sign, don’t sign it merely because someone tells you it’s routine.
And if you’re dealing with a serious injury and don’t understand whether an insurance company’s position is reasonable, talk to an experienced personal injury lawyer.
Information gives you the ability to make your own decisions.
The Biggest Lesson I Take From Oklahoma
I don’t know how the Oklahoma cases will ultimately be decided.
Neither does anyone else at this point.
But I think the documents and allegations emerging from these cases deserve the attention of anyone who has ever had to make a serious insurance claim.
The part that stays with me is the enormous difference between the claim-payment rates reported before and after Allstate’s 1997 Albuquerque experiment.
According to the documents described by Oklahoma Watch and The Journal Record, the percentage of hail claims receiving payments reportedly went from 82.8% to 11.1%.
Whatever the courts ultimately determine about the current allegations, those numbers illustrate something consumers should understand:
The process used to evaluate a claim can matter enormously.
That’s true when someone is standing on a roof looking for hail damage.
And in my experience, it’s also true when an insurance company is evaluating the consequences of a car wreck.
Don’t Be Intimidated by the Insurance Company
Insurance companies deal with claims every day.
Most injured people don’t.
For you, this may be the first serious accident you’ve ever experienced.
For an insurance company, it may be one of thousands of claims being handled at any given time.
That difference in experience can make people feel as though the insurance company holds all the cards.
It doesn’t.
You have rights.
You can ask questions.
You can preserve evidence.
You can get medical care.
You can challenge decisions.
And you can have somebody in your corner whose responsibility is to represent your interests rather than the insurance company’s.
That’s what personal injury lawyers do.
At Christmas Injury Lawyers, we’ve spent decades representing injured people throughout South Carolina and dealing with insurance companies on their behalf.
If you’ve been seriously injured in an accident and you’re uncertain about what the insurance company is telling you, we’ll be glad to talk with you.
Sometimes the most important thing we can give somebody isn’t a lawsuit.
It’s an understanding of what they’re dealing with and what options they have.